
Ready or not? Succession will come
For many owners of food and agribusiness SMEs, succession sits on the long-term agenda rather than the immediate one. There is always another customer issue, recruitment problem or investment decision demanding attention. Yet every business will eventually face a change in ownership or leadership. Planning early gives the owner much more control over when and how that happens. Marty Murphy, our Head of Tax, explores why succession planning should start long before an owner is ready to step away.
The story first appeared in our 2026 Food & Agribusiness Report
Discover more insights like this in our 2026 Food & Agribusiness Report – Download Now!
Does your business have a succession plan in place?
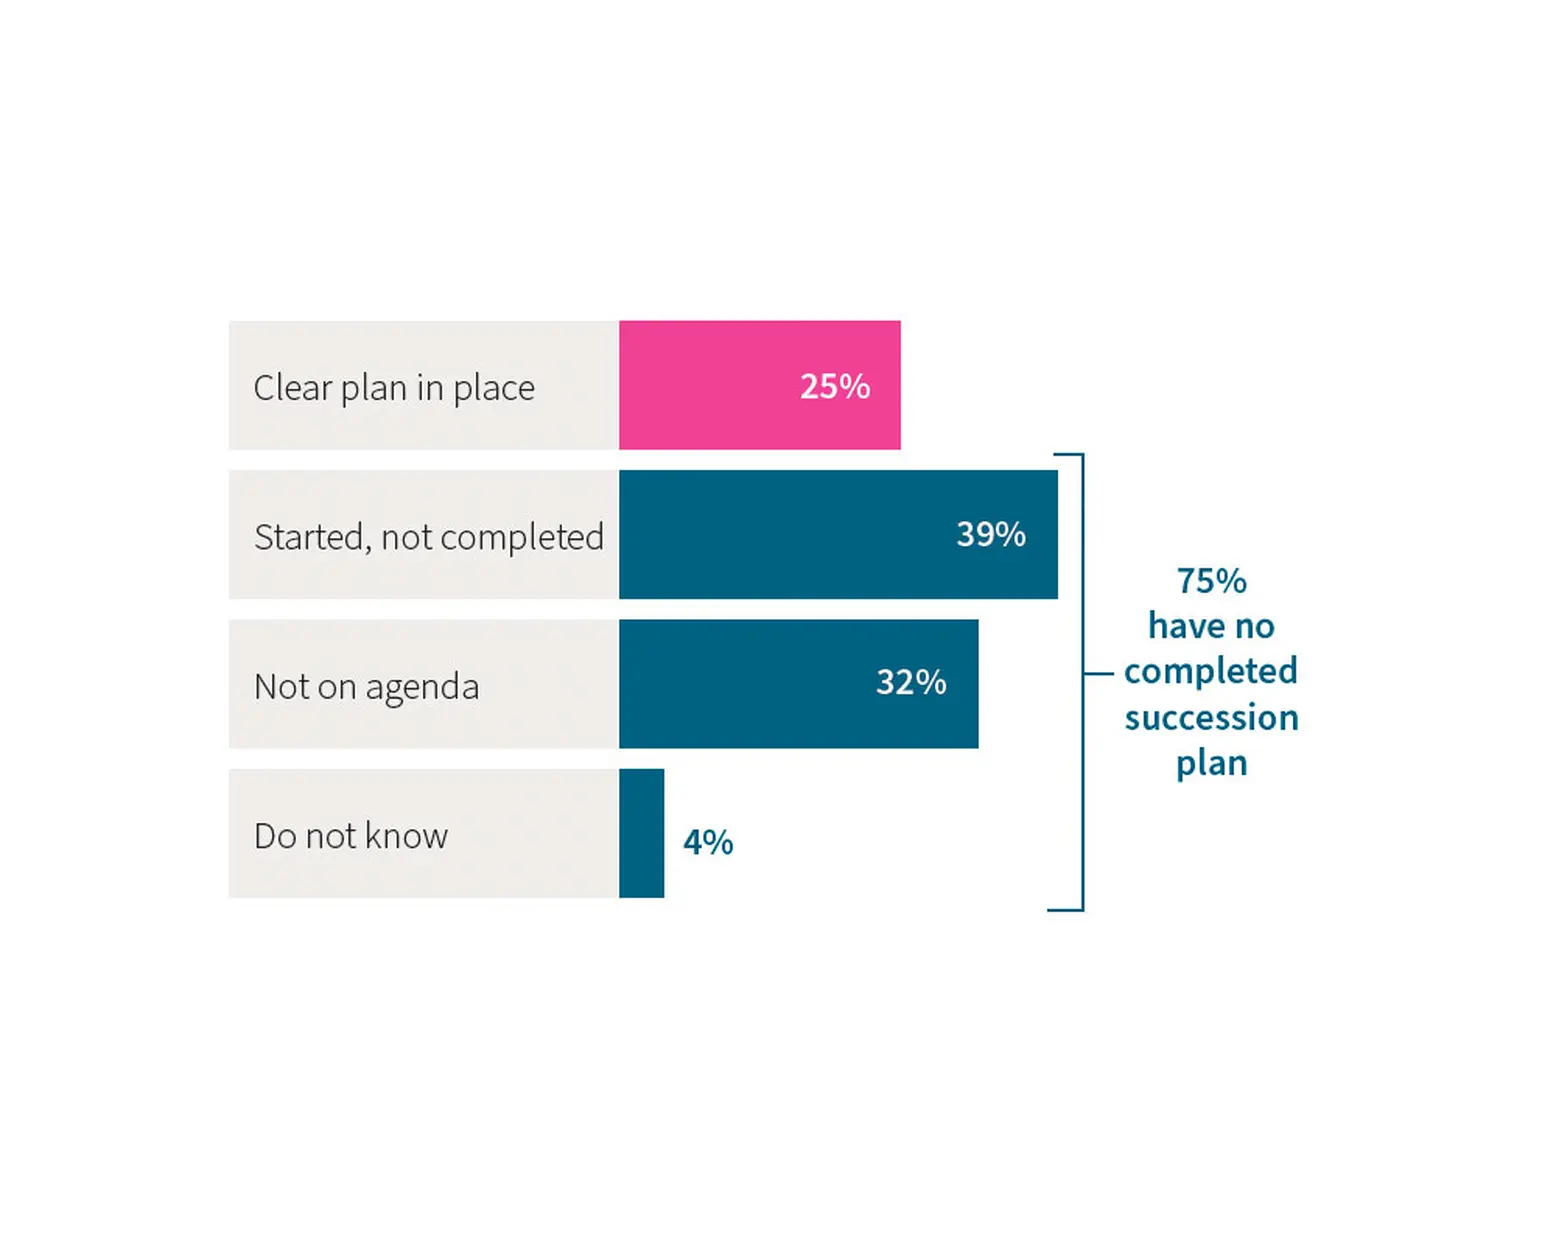
Just 25% of respondents have a clear succession or leadership transition plan in place, while a further 39% have started the process but have not completed it. For 32%, succession is not on the agenda at all. Overall, three quarters do not have a completed succession plan.
Consider a large agricultural machinery dealership built over 30 years. It may employ dozens of people, carry millions of euro of stock and represent major manufacturers. The owner may have longstanding relationships with suppliers, funders and customers, while also knowing which people inside the business can close a difficult sale, rescue an unhappy customer or manage stock through the season.
The shares in that company can be transferred quickly, the business cannot. Relationships with suppliers, banks, customers and staff do not automatically transfer with legal ownership, nor does authority built up over decades. A successor needs time to establish credibility, take responsibility and make decisions while the previous generation is still there to support them. Succession therefore needs to begin as a business discussion before it becomes a tax or legal exercise.
Who will run the business?
In some cases, the answer is obvious. One child may already be working in the business and have both the ability and desire to take it on. In others, several family members may bring different strengths. One may be commercially strong while another is better suited to finance, people or operations. The answer may also lie outside the immediate family, with a niece, nephew or long-serving management team taking a central role. In many SMEs, the eventual solution may be a combination of family ownership and professional management.
Who should own the business is a separate decision. Where some children work in the business and others do not, equal treatment does not necessarily mean identical ownership, voting rights or responsibilities. Different share classes, a family constitution or shareholders’ agreement can help separate economic ownership from control and set out how decisions are made, shares are transferred and family members enter or leave the business.
In other cases, a company purchase of shares or management buyout may provide an exit route for one family member while others continue. The proposed successor must also want the responsibility and have the ability to manage staff and retain the confidence of customers and suppliers. If one child has spent 15 years building the business while another has pursued a separate career, what does fair succession look like? These questions are easier to answer before ownership changes than afterwards.
The tax timetable
Once you know who is likely to take over, you can look at how and when ownership should transfer. One of the most valuable reliefs is Retirement Relief. Despite its name, an owner does not have to retire to claim it. Broadly, it can shelter Capital Gains Tax (CGT) on the transfer of qualifying business assets, including qualifying shares in a family company.
For transfers to children, the current rules create an important age distinction. Between 55 and 69, qualifying transfers can benefit from Retirement Relief up to an aggregate value of €10 million for transfers to children. Even for larger businesses, value above €10 million does not necessarily create an ultimate tax cost because the CGT on the excess can be deferred and will not ultimately become payable where the successor retains the qualifying assets for 12 years.
A more significant threshold for larger businesses is age 70, when the limit falls to €3 million. Where the business is worth materially more, the tax cost of a lifetime transfer can change dramatically. If that window is missed, an owner may find that a lifetime transfer becomes sufficiently expensive that they hold onto the business until death. Tax should support the succession plan, not dictate it.
Look at what is inside the company
Successful businesses often build up substantial cash reserves or acquire investment property, portfolios and other assets outside the core trade. Those assets matter when Retirement Relief and Business Relief are considered.
Business Relief from Capital Acquisitions Tax (CAT) can reduce the taxable value of qualifying business property passing by gift or inheritance by 90%. However, it should not be assumed that everything inside a company will qualify. Investment businesses are excluded and non-business assets can fall outside the relief, which can include cash in excess of the requirements of the trade. Retirement Relief similarly applies to qualifying chargeable trading assets, so chargeable investment assets within a company or group can restrict the tax relief.
The practical step is to review the balance sheet early, particularly where significant cash, investment property or other non-trading assets have accumulated. There may be commercial and tax reasons to reorganise the structure before succession.
Stamp Duty also needs to be included in the plan. Retirement Relief and Business Relief can substantially reduce CGT and CAT, but a lifetime gift of shares can still give rise to Stamp Duty by reference to market value. For ordinary shares, the standard rate is generally 1% where the special higher rate for certain property-rich companies does not apply. On a valuable SME, that can still be a meaningful cash cost.
What if succession happens tomorrow?
A succession plan also needs to work if events do not follow the intended timetable. An owner may plan to transfer the business at 62, 65 or 68, but illness, incapacity or death can intervene much earlier.
For the machinery dealer, the questions are immediate. Who can deal with the bank, approve a major stock purchase, negotiate with the manufacturer or make a decision on staff and customer credit if the owner is suddenly unavailable? If nobody can answer those questions, there is a business-continuity problem before there is a tax problem.
Wills and shareholders’ agreements should therefore form part of the succession process. Where there are several shareholders, valuation methods and the mechanism for buying out an interest on death or serious illness should be agreed in advance. Shareholder protection, cross-option arrangements and key-person insurance may also have a role.
Five steps to start
1 Decide who can run the business
If you were unavailable for six months tomorrow, who would take control? Identify the people capable of leading the company and maintaining its key relationships and start filling any gaps.
2 Decide who should own it
Speak to the family and proposed successors. Decide whether ownership should differ between active and non-active family members and whether different voting rights, a shareholders’ agreement, family constitution or buyout mechanism is needed.
3 Value the business and understand the tax position
Establish what the business is worth, where the value sits and what assets are held in the company or group. Review Retirement Relief, Business Relief and Stamp Duty while there is still time to make changes.
4 Plan for illness, incapacity or death
Review the will, shareholder arrangements, decision-making authority and insurance position so the business can continue if an owner dies or becomes unavailable.
5 Start transferring the business before transferring the shares
Bring the next generation or management team into the meetings that matter. Let suppliers, finance providers and key customers deal with them. Give them responsibility while the current owner is still there to support them.
